If you are planning a major home improvement project, the question of how to fund it tends to arrive fairly quickly. A renovation loan is one of the most practical routes available, but there is often confusion about what it actually covers. Does it extend to every room? Are there limits on what work qualifies? The answer is more flexible than most people expect, with a few important caveats.
What is a renovation loan?
A renovation loan is a form of borrowing specifically designed to fund home improvement work. In the UK, this typically comes as an urgent bridging loan (borrowing against the equity in your property) or an unsecured personal loan for smaller projects. Some lenders also offer specialist products tied to specific types of work, such as energy efficiency improvements.
The key distinction from a standard personal loan is that renovation loans are generally assessed, at least in part, on the value the work will add to the property, not just your income and credit history alone.
Room-by-room: What is typically covered?
Kitchen
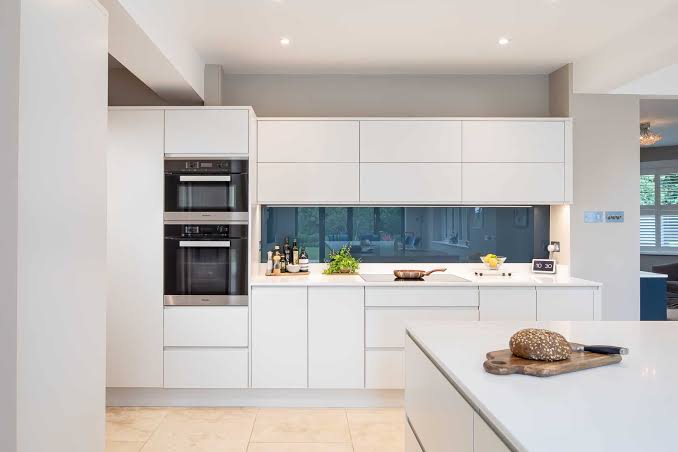
The kitchen is the most commonly funded renovation space, and lenders are well used to it. Costs covered typically include:
- Full kitchen replacements (units, worktops, appliances)
- Structural changes such as knocking through walls to create an open-plan layout
- New flooring, lighting, and electrics specific to the kitchen
- Plumbing work including sink relocation or boiler repositioning
Because a well-executed kitchen renovation adds measurable value to a property, lenders rarely push back on this category.
Bathroom and en suite
Bathrooms rank alongside kitchens as the highest-return rooms for renovation spend. A renovation loan will generally cover:
- Full bathroom suites (bath, shower, basin, toilet)
- Tiling, flooring, and waterproofing
- Plumbing and pipework alterations
- Extraction ventilation and electrics
- Adding an en suite where one did not previously exist
Living room and dining room
These rooms are covered, though lenders tend to scrutinise the scope of work more carefully. Straightforward cosmetic updates; new carpets, repainting, replastering, may be considered too minor for a renovation loan and better suited to an unsecured personal loan. Where the scope includes structural changes, new windows, or rewiring, most lenders are comfortable.
Covered work typically includes:
- Structural changes such as opening up between two rooms
- Window and door replacements
- Full replastering and rendering
- Electrical rewiring or upgrading consumer units
- Installing log burners or fireplaces (subject to planning and building regs)
Bedrooms
Bedroom renovations are covered on much the same basis as living rooms. The work needs to represent a meaningful improvement rather than routine maintenance. Loft conversions that create a new bedroom are particularly well received by lenders, they typically result in a significant uplift in property value and are among the most straightforward projects to get funded.
Covered work includes:
- Loft conversions with proper structural and insulation work
- Built-in wardrobes and storage where integrated into a wider renovation
- Rewiring and new lighting circuits
- Insulation upgrades
Extensions and garden rooms
Single-storey extensions, double-storey extensions, orangeries, and outbuildings that form usable living space are all within scope for a renovation loan. This is one area where lenders will often want to see planning permission documentation and contractor quotes before agreeing terms.
Cellar and basement conversions
Converting an unused cellar into a habitable room, whether a home office, gym, or bedroom, is covered. Tanking (waterproofing the walls and floor), insulation, structural underpinning, and ventilation all fall within what lenders will fund. These projects tend to involve higher costs and more extensive structural surveys, so expect more documentation to be requested.
Utility room and laundry space
Utility rooms are included within renovation loan scope when they form part of a broader project. A standalone utility room update is unlikely to meet the threshold on its own, but if it sits alongside a kitchen renovation or extension, it is generally bundled in without issue.
Home office
The post-pandemic shift toward remote working has made the home office renovation a recognised category. Lenders increasingly treat dedicated home office conversions, particularly those involving new builds, insulated garden offices, or garage conversions, as eligible improvement work.
Garage conversions
Converting a garage into a bedroom, office, or living space is one of the most cost-effective ways to add square footage to a property, and it is well within the scope of a renovation loan. Lenders will typically expect insulation, damp proofing, window installation, and electrics to be included in the project specification.
Refurbishment financeComplete refurbishment worksPerfect for investors and BTL landlords to improve properties to increase yieldWhy refurb loans?Light refurbHeavy refurbCommercial and BTL propertyGet refurbishment fundingWhat is typically not covered?
It is worth being clear on the limits. Renovation loans are designed for structural and meaningful cosmetic improvements, not routine upkeep. Work that generally falls outside what lenders will fund includes:
- Decoration only (painting, wallpaper, soft furnishings)
- Routine maintenance such as fixing a leaking roof tile or replacing a broken boiler on a like-for-like basis
- Garden landscaping unconnected to a building project
- Swimming pools in most cases
- Luxury or purely aesthetic additions that do not increase the usable space or structural integrity of the property
A note on structural vs cosmetic work
Most lenders draw a clear line between structural improvement and cosmetic refreshes. A full bathroom suite replacement with new tiling and plumbing is structural, it changes the fabric of the room. Buying a new mirror and repainting the walls is not.
If your project sits across both categories, the loan is usually calculated against the qualifying structural elements. The cosmetic portion may need to be self-funded or covered separately.
What lenders will want to see
Regardless of the room, most renovation loan applications will require:
- A detailed scope of works, ideally from a qualified contractor
- Quotes or estimates for the total project cost
- Planning permission documentation where applicable (extensions, loft conversions, outbuildings)
- Evidence of building regulations compliance for structural work
- In some cases, a surveyor’s report confirming the uplift in property value
Getting these in order before you apply will speed up the process considerably and gives the lender confidence that the money will be used as stated.
The takeaway
A renovation loan can cover the full breadth of a property, from the basement to the loft, provided the work represents a genuine improvement to the fabric or usable space of the home. The strongest applications involve structural projects with measurable value uplift: kitchen and bathroom refits, extensions, loft and garage conversions, and full room rewires or replasters. The clearer your scope of works and the more documentation you have ready, the smoother the process will be. If your project spans multiple rooms, present it as a single cohesive programme of works rather than a series of individual jobs, lenders respond better to a joined-up plan.